When the 120th Congress takes office on January 3, 2027, the new majority has many promises to fulfill. Honestly, there’s not much the legislative branch can do if the sitting president threatens to veto any legislation that reaches his desk.
Housing affordability affects everyone, regardless of ideology. Younger people can’t afford to buy their first homes. Renters struggle to keep up with rising costs. Older Americans worry about finding housing that fits their budgets and changing needs.
It’s worth asking whether the traditional American dream of homeownership is still attainable for the next generation. Plenty of existing housing programs can be tweaked administratively, provided the various executive departments are willing to bend, given presidential threats to disallow any substantive changes.
After World War II, returning veterans and their families helped fuel an extraordinary housing boom. The GI Bill provided mortgage guarantees that encouraged private lenders to finance home purchases on favorable terms.
I, along with three colleagues, rented a house in Gillette, Wyoming when we landed our first jobs there. Tom, a Vietnam War veteran, asked us if we wanted to buy a house together. We couldn’t turn down a 100 percent loan guarantee, so we bought a brand-new split-level home in a new subdivision.
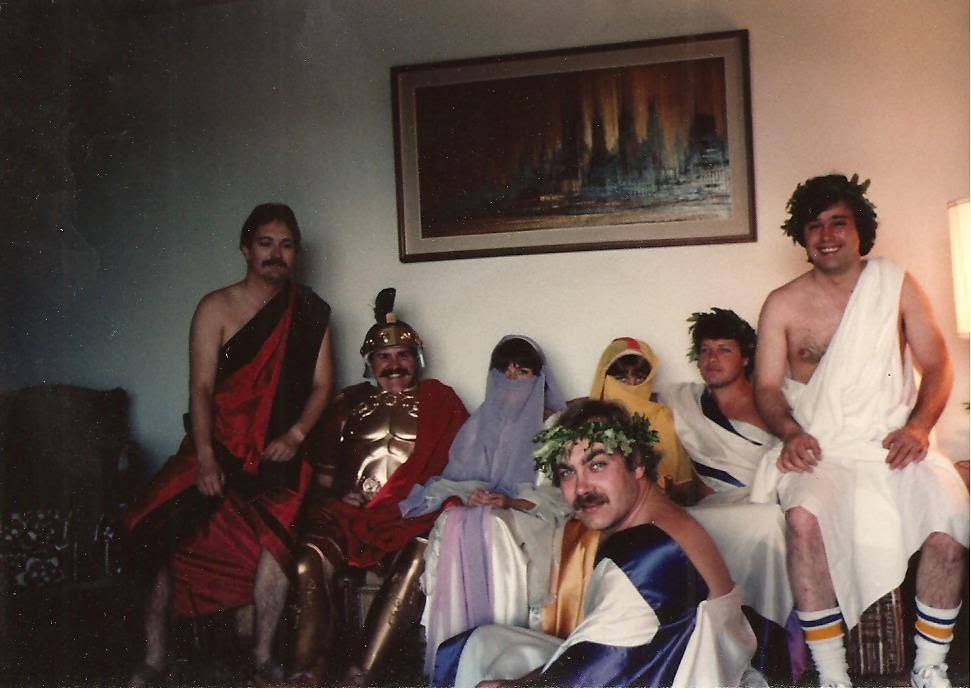
Our house became known as the 3003 Club, where Mom is never home.
FHA mortgage insurance also helped make long-term mortgages more accessible, including my first condo purchase in Boulder. Private builders responded with mass-produced suburban developments, offering modest houses on individual lots.
For millions of families, particularly during the baby-boom years, the formula worked: find a job, obtain an affordable mortgage, buy a house and raise a family. The federal government didn’t build all those houses. It helped create the financial conditions that encouraged private developers and lenders to make homeownership possible.
That postwar model had serious shortcomings. Black veterans and other minorities frequently encountered discriminatory lending practices, restrictive covenants, and redlining that denied them equal access to the benefits. We shouldn’t romanticize a system that excluded so many Americans. The underlying idea of using public policy to encourage private investment in housing remains worth considering.
Today’s economics are considerably different. Land costs more, construction materials and labor are expensive, mortgage rates and down-payment requirements put homeownership out of reach for many households, and desirable locations often have restrictive zoning and limited housing supply.
The modest postwar house on a single suburban lot, financed with a government-backed mortgage, isn’t a realistic option for today’s young families, at least not in many of the places where jobs and opportunities are concentrated.
Another development worth examining is the growing presence of large institutional investors and corporate landlords in the housing market. Some companies have purchased existing single-family homes in bulk, converting what might otherwise have been owner-occupied houses into rental properties. Others have developed entire neighborhoods of homes intended for rent rather than sale.
There is nothing inherently wrong with rental housing or private investment. Many people need or prefer to rent. But when large companies accumulate substantial housing portfolios, particularly in concentrated local markets, questions arise about competition, affordability, and the landlord-tenant relationship.
Corporate ownership can bring economies of scale, but it can also create opportunities for exploitation. Tenants have raised concerns about escalating rents, additional fees, maintenance problems, and dealing with distant corporate management rather than a local property owner. When a handful of large operators control a significant share of rental homes in a neighborhood, tenants may have fewer alternatives.
This isn’t an argument that institutional investors own most American homes. They don’t, but their influence can be considerably greater in particular metropolitan areas and neighborhoods than national statistics suggest. Congress should pay attention to local market concentration, require greater transparency in corporate ownership and rental practices, and make sure competition laws protect both prospective homeowners and renters.
So what can Congress realistically do?
I don’t think either party wants the federal government to become a national homebuilder. Nor should that be the starting point. Housing in America has largely been a private-market function. Builders, developers, lenders, investors, and local governments determine what gets built and where.
The federal government’s more useful role is to encourage private investment and make existing housing programs work better.
Rather than inventing another massive federal housing bureaucracy, Congress could tweak and amend existing programs. Here are some common threads:
- Modernize mortgage guarantees. Improve existing FHA, VA, and USDA loan programs to help qualified first-time buyers obtain financing without taking on unreasonable financial risks. If Congress wants changes, it will have to work with lenders. Banks want to make more money, and expanding the number of potential borrowers should be a good problem to solve.
- Encourage starter-home construction. Use existing tax incentives and financing programs to encourage private builders to construct smaller, more affordable houses, townhomes, and duplexes. Private sector approaches could be scaled, such as expanding the owner sweat equity model used by Habitat for Humanity.
- Expand affordable rental development. Improve existing Low-Income Housing Tax Credit and HOME programs to attract private investment in reasonably priced rental housing. This is the U.S. Department of Housing and Urban Development’s primary business.
- Reward communities that make room for housing. Use federal infrastructure and housing grants to encourage local governments to streamline permitting and allow more residential construction near jobs, transportation, and services.
- Encourage alternative construction. Support modular and manufactured housing, updated building techniques, and other approaches that can reduce construction time and costs. This is largely a local issue because building codes govern construction.
- Protect renters and prospective homeowners. Improve transparency in corporate ownership, rental fees, and property management, and examine practices that reduce competition in local housing markets. This is a place for national legislation. Whether Congress has the will to buck big construction and investors in the “own-to-rent” conversions is a big unknown.
No single federal program will solve the housing shortage. Congress can’t dictate what a house should cost in Boulder, Boise, or Birmingham. Local zoning, land availability, permitting, and infrastructure decisions matter enormously.
Congress can use the programs and financial tools it already has to encourage private developers to build more housing at prices people can afford.
The objective shouldn’t be to recreate the suburbs of the 1950s. It should give the next generation a reasonable chance to achieve the same economic security that homeownership provided to millions of postwar families.
The American dream shouldn’t depend on inheriting a house from your parents.

